01 Read
What happened
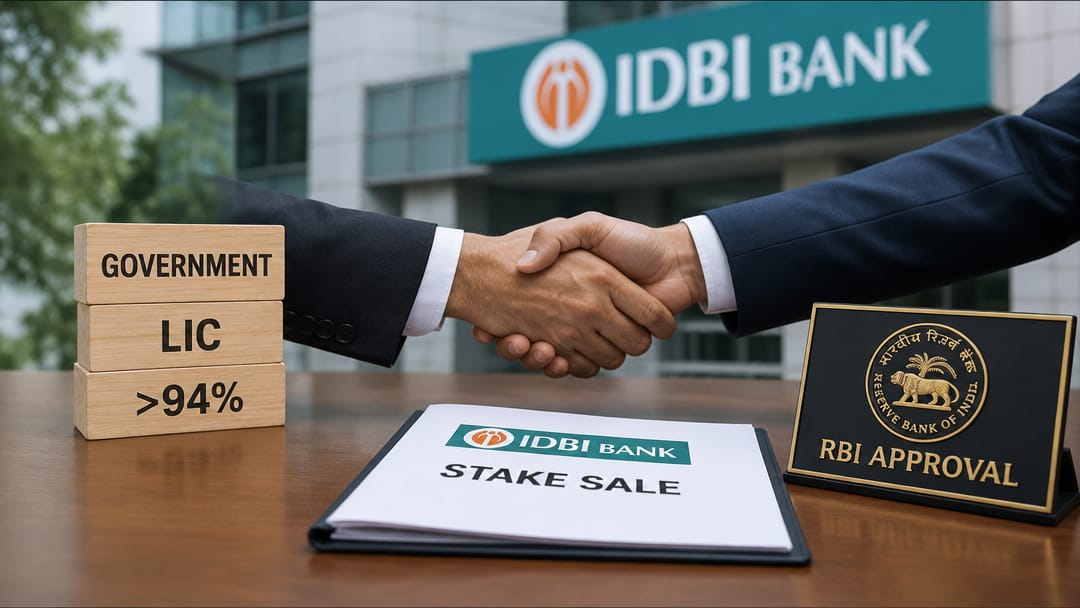
India's strategic disinvestment of IDBI Bank involves selling a substantial government equity stake to a private buyer along with transfer of management control. The government and LIC together hold over 94% in IDBI Bank. The process allows flexibility in structuring the deal, including permitting the acquirer to retain IDBI's banking licence. RBI approval is mandatory for any change in ownership of a private bank, making this a rare case of a PSU bank transitioning to private hands.
02 Understand
Why it matters
Strategic disinvestment differs from mere stake sale. In ordinary disinvestment, the government reduces its shareholding but retains control. In strategic disinvestment, management control is transferred to a private entity — the government exits the business of running the enterprise. IDBI Bank is a distinctive case because it sits at the intersection of two regulatory worlds: it is a scheduled commercial bank (regulated by RBI) and a company under the Companies Act, with LIC as its majority shareholder.
For the disinvestment to succeed, the acquirer must receive a 'fit and proper' clearance from RBI under the Banking Regulation Act, 1949. This is not a formality — RBI's Guidelines for Licensing of New Private Sector Banks and its fit-and-proper criteria apply. The government has indicated flexibility on the exact quantum of stake to be sold, as long as management control transfers.
The policy rationale is fiscal: proceeds go to the Consolidated Fund of India, not earmarked but used to finance the fiscal deficit. From a financial inclusion angle, the transition raises questions about whether a privately managed IDBI Bank will continue priority sector lending (PSL) obligations — it will, because PSL norms apply to all scheduled commercial banks regardless of ownership. From a capital market angle, SEBI's SAST (Substantial Acquisition of Shares and Takeovers) Regulations are relevant to the open-offer requirement that a strategic acquirer must follow if crossing the 25% trigger in a listed entity.
For the disinvestment to succeed, the acquirer must receive a 'fit and proper' clearance from RBI under the Banking Regulation Act, 1949. This is not a formality — RBI's Guidelines for Licensing of New Private Sector Banks and its fit-and-proper criteria apply. The government has indicated flexibility on the exact quantum of stake to be sold, as long as management control transfers.
The policy rationale is fiscal: proceeds go to the Consolidated Fund of India, not earmarked but used to finance the fiscal deficit. From a financial inclusion angle, the transition raises questions about whether a privately managed IDBI Bank will continue priority sector lending (PSL) obligations — it will, because PSL norms apply to all scheduled commercial banks regardless of ownership. From a capital market angle, SEBI's SAST (Substantial Acquisition of Shares and Takeovers) Regulations are relevant to the open-offer requirement that a strategic acquirer must follow if crossing the 25% trigger in a listed entity.
Remember + Why it matters
The key recall facts and exact examiner angle for SEBI Grade A are in the Crux app.
01
Key figure and date from this topic
02
Specific number or threshold to remember
03
Policy or regulatory implication
Read + Understand free forever · 30-day free trial