01 Read
What happened
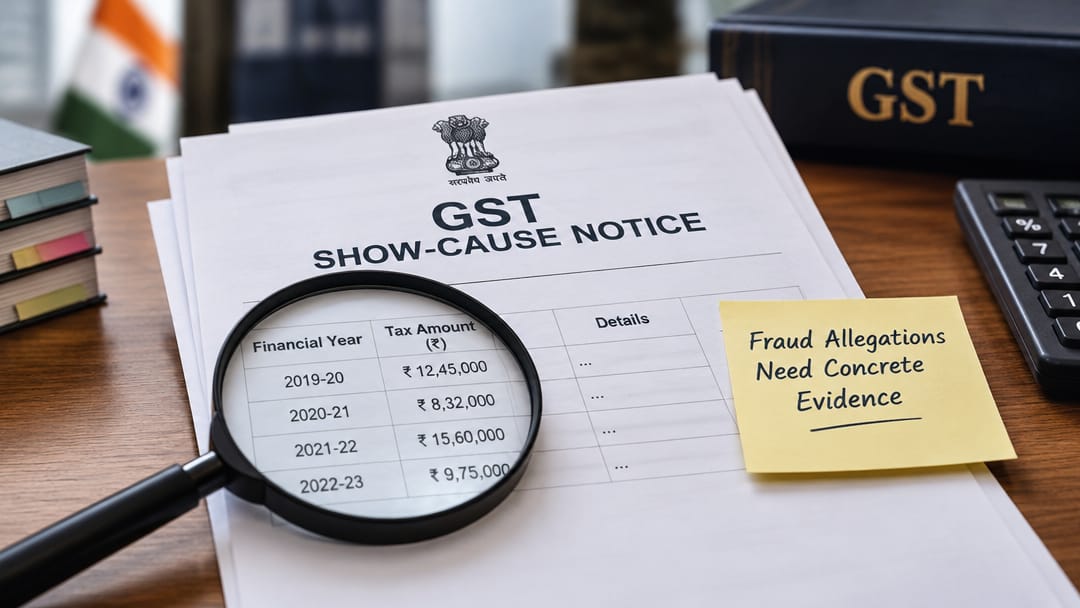
Tax authorities have been instructed that a single show-cause notice cannot bundle multiple years of GST demands without specifying the tax amount owed for each year individually. Officers must also substantiate fraud allegations with concrete evidence rather than making blanket claims. This procedural reform is aimed at improving taxpayer rights and enforcement quality under the GST framework, ensuring that notices are precise, year-specific, and legally defensible before adjudication proceeds.
02 Understand
Why it matters
A show-cause notice (SCN) under the GST Act is the first formal step in tax demand proceedings. Previously, officers sometimes clubbed multiple financial years into a single notice, making it difficult for taxpayers to understand or contest the specific demand for each period. The new instruction mandates year-wise disaggregation of tax demands within every SCN.
This reform has two key dimensions. First, procedural clarity: each year's demand must carry its own tax quantum, so the taxpayer knows exactly what is being alleged for each period. Second, evidentiary burden: if an officer alleges fraud, suppression, or wilful misstatement — provisions that extend the limitation period for issuing notices from 3 years to 5 years under Section 74 of the CGST Act — the allegation must be backed by substantive evidence, not assumed.
For NABARD aspirants, this matters because GST compliance affects agri-input suppliers, rural cooperative businesses, and entities that NABARD refinances. Unjustified multi-year bundled notices can disrupt cash flows, inflate working capital needs, and indirectly raise the cost of rural credit. GST enforcement quality is therefore a fiscal governance issue with downstream effects on agricultural credit ecosystems and cooperative bank operations.
This reform has two key dimensions. First, procedural clarity: each year's demand must carry its own tax quantum, so the taxpayer knows exactly what is being alleged for each period. Second, evidentiary burden: if an officer alleges fraud, suppression, or wilful misstatement — provisions that extend the limitation period for issuing notices from 3 years to 5 years under Section 74 of the CGST Act — the allegation must be backed by substantive evidence, not assumed.
For NABARD aspirants, this matters because GST compliance affects agri-input suppliers, rural cooperative businesses, and entities that NABARD refinances. Unjustified multi-year bundled notices can disrupt cash flows, inflate working capital needs, and indirectly raise the cost of rural credit. GST enforcement quality is therefore a fiscal governance issue with downstream effects on agricultural credit ecosystems and cooperative bank operations.
Remember + Why it matters
The key recall facts and exact examiner angle for NABARD Grade A are in the Crux app.
01
Key figure and date from this topic
02
Specific number or threshold to remember
03
Policy or regulatory implication
Read + Understand free forever · 30-day free trial