01 Read
What happened
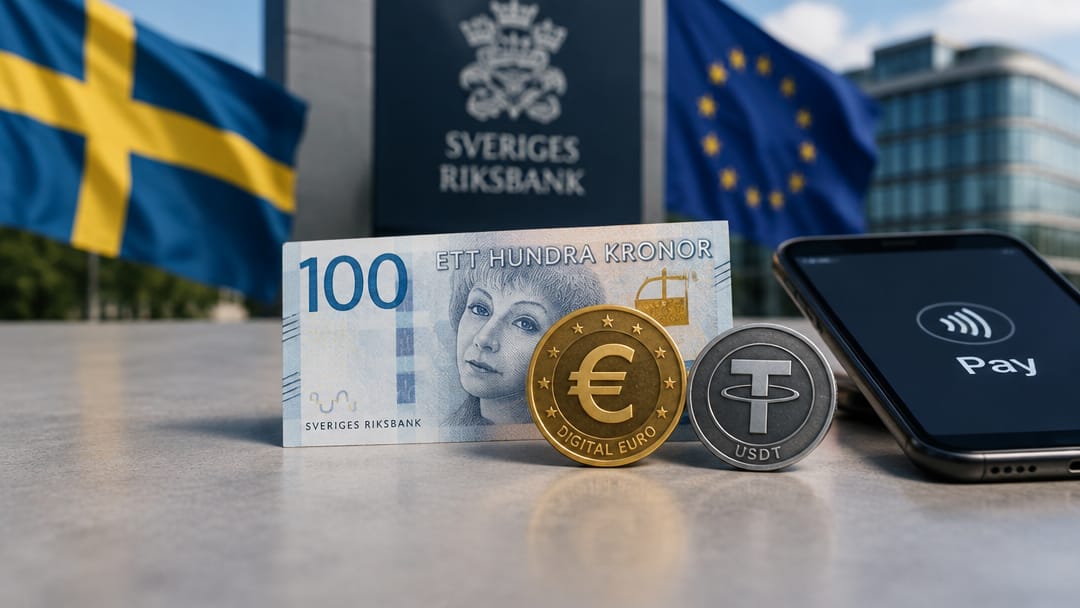
Sweden's central bank, the Riksbank, has revived the e-krona debate, warning that the European Central Bank's planned digital euro and the rise of private stablecoins could erode the Swedish krona's role in domestic and cross-border payments. The Riksbank argues that without a central bank digital currency of its own, Sweden risks losing monetary sovereignty as privately issued and foreign digital currencies increasingly intermediate everyday transactions.
02 Understand
Why it matters
A Central Bank Digital Currency (CBDC) is a digital form of sovereign money issued directly by a central bank — essentially a digital equivalent of cash, carrying no credit risk because it is a direct liability of the issuing authority.
Sweden is an unusually instructive case because it is among the world's most cashless societies, making it a real-world stress test for what happens when physical currency fades. The Riksbank launched its e-krona pilot in 2020, but no final decision to issue has been made.
The current concern has two triggers:
1. The ECB's digital euro project — if adopted, EU citizens (and, by extension, residents of non-euro countries closely integrated with the eurozone like Sweden) could transact in a foreign CBDC, reducing demand for the domestic currency.
2. Stablecoins (private digital tokens pegged to fiat currencies) — their growing use in payments could fragment the monetary transmission mechanism, weakening a central bank's ability to implement interest-rate policy.
For India, the RBI launched its own CBDC — the Digital Rupee (e₹) — in two tracks: the wholesale pilot (e₹-W) in November 2022 and the retail pilot (e₹-R) in December 2022. The RBI's stated rationale mirrors the Riksbank's concern: preserving monetary sovereignty, reducing settlement risk, and providing a programmable, interoperable alternative to private stablecoins.
Exam relevance: CBDC architecture (account-based vs token-based), two-tier distribution model, and the distinction between wholesale and retail CBDC are all active testing zones for RBI Grade B and UPSC GS-III.
Sweden is an unusually instructive case because it is among the world's most cashless societies, making it a real-world stress test for what happens when physical currency fades. The Riksbank launched its e-krona pilot in 2020, but no final decision to issue has been made.
The current concern has two triggers:
1. The ECB's digital euro project — if adopted, EU citizens (and, by extension, residents of non-euro countries closely integrated with the eurozone like Sweden) could transact in a foreign CBDC, reducing demand for the domestic currency.
2. Stablecoins (private digital tokens pegged to fiat currencies) — their growing use in payments could fragment the monetary transmission mechanism, weakening a central bank's ability to implement interest-rate policy.
For India, the RBI launched its own CBDC — the Digital Rupee (e₹) — in two tracks: the wholesale pilot (e₹-W) in November 2022 and the retail pilot (e₹-R) in December 2022. The RBI's stated rationale mirrors the Riksbank's concern: preserving monetary sovereignty, reducing settlement risk, and providing a programmable, interoperable alternative to private stablecoins.
Exam relevance: CBDC architecture (account-based vs token-based), two-tier distribution model, and the distinction between wholesale and retail CBDC are all active testing zones for RBI Grade B and UPSC GS-III.
Remember + Why it matters
The key recall facts and exact examiner angle for RBI Grade B are in the Crux app.
01
Key figure and date from this topic
02
Specific number or threshold to remember
03
Policy or regulatory implication
Read + Understand free forever · 30-day free trial