SEBI revises Closing Auction Session rules, effective 7 December 2026
What happened
SEBI has revised the framework governing the Closing Auction Session (CAS), the price-discovery mechanism used to determine a stock's official closing price on Indian exchanges. The revised rules are set to take effect from 7 December 2026. CAS was introduced to reduce last-minute price manipulation by aggregating buy and sell orders in a brief window before market close. The revision updates operational parameters of this session, affecting all equity traders on recognised stock exchanges in India.
Why it matters
The Closing Auction Session (CAS) is a structured window at the end of the continuous trading session during which buy and sell orders are collected and matched at a single equilibrium price — the official closing price of a security. India adopted CAS to align with global best practices and reduce the manipulation risk that existed when the closing price was simply the last traded price.
In the CAS mechanism, orders placed during the auction window are queued and matched at a single price that maximises volume. This price then becomes the official closing price used for index calculation, NAV computation of mutual funds, and settlement benchmarks.
SEBI's 2026 revision updates the operational rules — likely covering the duration of the order-entry window, call auction timings, price bands applicable during CAS, and eligibility of securities. These details matter because they directly affect how institutional investors, index funds, and ETFs execute end-of-day trades.
From an exam perspective, understanding CAS connects to broader SEBI syllabus areas: market microstructure, price discovery, manipulation prevention, and the regulatory architecture of stock exchanges. SEBI has historically revised trading session frameworks through circulars, and the examiner tests both the conceptual purpose of such mechanisms and the institutional detail — which regulator mandated it, which exchanges implement it, and when revisions come into force.
JioBlackRock files draft schemes with SEBI: life cycle and debt funds join the queue
What happened
JioBlackRock Mutual Fund, the joint venture between Reliance's Jio Financial Services and BlackRock, has filed draft scheme information documents with SEBI to launch two new funds: a JioBlackRock Life Cycle Fund and a debt fund. The filing marks the AMC's formal product-expansion move after receiving SEBI registration. These are open-ended schemes pending SEBI's observation letter before public subscription can commence.
Why it matters
When an asset management company (AMC) wants to launch a new mutual fund scheme in India, it must first file a Draft Scheme Information Document (DSID) with SEBI. SEBI then reviews the draft and issues an 'observation letter' — popularly called approval — typically within 21 working days. Only after receiving this letter can the AMC open a New Fund Offer (NFO) to the public.
JioBlackRock Mutual Fund is a joint venture between Jio Financial Services Ltd (a Reliance Industries subsidiary) and BlackRock Inc., the world's largest asset manager. The JV received its SEBI AMC registration in 2024, making it a new entrant in India's crowded mutual fund industry.
The two schemes filed are significant for their design: a Life Cycle Fund is typically an asset-allocation fund that automatically shifts from equity-heavy to debt-heavy portfolios as the investor ages or approaches a target date, making it suitable for long-term retirement planning. A debt fund invests predominantly in fixed-income instruments.
For SEBI Grade A aspirants, this filing sits at the intersection of mutual fund regulation (SEBI MF Regulations 1996), the NFO process, scheme categorisation norms (SEBI's October 2017 circular on scheme categorisation), and the regulatory oversight role of SEBI over AMCs. The JioBlackRock JV also tests knowledge of institutional promoters and foreign-domestic partnership structures in the financial sector.
IFSCA lets fintech firms test products in GIFT City without a full licence
What happened
The International Financial Services Centres Authority introduced its FinTech Sandbox Framework in 2026, allowing fintech entities to test innovative financial products and services within GIFT City's IFSC under relaxed regulatory conditions before obtaining a full licence. Firms operating inside the sandbox may maintain an INR account solely for administrative expenses but must record accounts in a freely convertible currency. The framework sits atop IFSCA's existing 2020 regulations and is designed to balance innovation with investor protection.
Why it matters
A regulatory sandbox is a controlled environment where innovators can test new financial products with real customers under a regulator's supervision, but with temporary exemptions from some standard rules. IFSCA — the unified regulator for India's International Financial Services Centres, primarily GIFT City in Gujarat — introduced this framework to lower the barrier for fintech startups that cannot afford full compliance costs before proving their concept works.
The key regulatory logic is asymmetry of risk: sandbox firms get relaxed norms during a defined testing window, but the regulator retains the right to revoke, modify, or refuse a full licence if the test reveals systemic risks. This protects investors while encouraging innovation.
The currency rule is exam-critical: sandbox entities must maintain books in a freely convertible foreign currency (not INR), but are permitted one INR account exclusively for administrative expenses. This mirrors the broader IFSC architecture, where transactions are dollar- or foreign-currency-denominated to integrate with global capital markets.
For SEBI aspirants, sandboxes matter because SEBI also runs its own regulatory sandbox (notified 2020) for securities-market innovators. IFSCA's framework extends this concept specifically to the IFSC jurisdiction. The distinction between IFSCA's remit (IFSC-based entities) and SEBI's remit (domestic securities markets) is a classic examiner boundary question. Knowing which regulator governs which sandbox, under which parent statute (IFSCA Act 2019 vs. SEBI Act 1992), is the precision that separates scores.
SC rules CoC cannot walk back an approved insolvency plan once creditors have voted
What happened
The Supreme Court on October 26 ruled that a Committee of Creditors cannot withdraw its approval of a resolution plan after voting in favour of it, even if the corporate debtor's financial position has improved since the vote. The Court held that CoC approval, once given, binds the process and cannot be reversed on commercial grounds. The ruling reinforces the finality of the insolvency resolution process under the Insolvency and Bankruptcy Code, 2016.
Why it matters
Under the Insolvency and Bankruptcy Code (IBC), 2016, once a Committee of Creditors approves a resolution plan by the required majority (66% voting share), the plan moves toward NCLT approval and eventual implementation. The CoC functions as the commercial decision-maker within the Corporate Insolvency Resolution Process (CIRP), but its authority is procedurally bounded — it cannot revisit a concluded vote simply because circumstances have changed.
This judgment addresses a situation where creditors, having approved a resolution plan, later sought to withdraw that approval citing improved financial health of the debtor. The Supreme Court rejected this, holding that the IBC does not contemplate a withdrawal mechanism at the post-approval stage on such grounds. The resolution plan, once approved by CoC, is meant to be submitted to NCLT under Section 30(6), and the CoC cannot stall or reverse this by claiming better recovery prospects now exist.
The significance for exam purposes is layered: (1) it tests understanding of the CoC's role and its limits under the IBC; (2) it clarifies that commercial wisdom of CoC, while wide in scope, is not unlimited in time — it crystallises at the point of voting; (3) it reinforces the IBC's core objective of time-bound resolution. For CLAT PG aspirants, this connects to questions on CoC powers, CIRP timelines, and the finality of resolution plans, all of which have been tested through statutory identification and case-law classification templates.
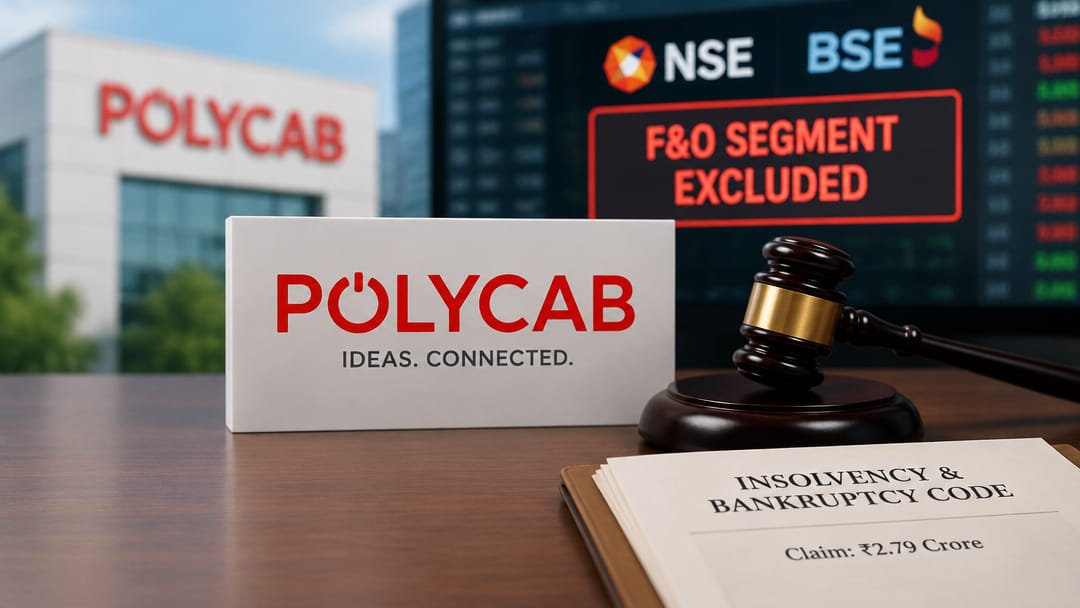
Polycab lost F&O access over a ₹2.79-crore claim, NCLAT stay notwithstanding
What happened
Polycab India, a ₹1.1-lakh-crore market-cap company with annual revenue of ₹29,100 crore, was removed from the Futures and Options segment after a vendor filed an insolvency claim of just ₹2.79 crore under the Insolvency and Bankruptcy Code. Despite Polycab obtaining a stay from the National Company Law Appellate Tribunal, NSE and BSE proceeded with the F&O exclusion, exposing how IBC proceedings can trigger exchange-level market access consequences regardless of appellate relief.
Why it matters
This episode sits at the intersection of insolvency law, exchange regulations, and listed-company governance — a triangle the SEBI Grade A examiner finds fertile.
Under SEBI's framework, stock exchanges can exclude a scrip from the F&O segment if it faces admission of an insolvency petition under the IBC, 2016. The trigger is the admission of the petition by the NCLT, not its final adjudication. An appellate stay by NCLAT suspends the operational effect of the NCLT order in a legal sense, but exchanges interpret their own circulars strictly: once the admission threshold is crossed, the risk-management logic kicks in independently.
This creates a procedural paradox: a company with fundamentally sound financials and an active appellate remedy can still lose derivative-market access because exchange eligibility norms do not automatically track tribunal-level stays. SEBI's F&O eligibility criteria — set out in its circulars on derivatives market — include financial health, market-cap, and liquidity thresholds, but also regulatory/legal encumbrances.
For exam purposes, the key conceptual distinction is between the legal effect of a stay (suspending the NCLT order) and the exchange's risk-management action (an independent regulatory response to a litigation event). SEBI has the power to direct exchanges on eligibility, but exchanges retain operational discretion within those guidelines. The examiner is likely to test: what triggers F&O exclusion, which authority admits an IBC petition (NCLT), which body hears appeals (NCLAT), and whether a stay automatically restores exchange access.