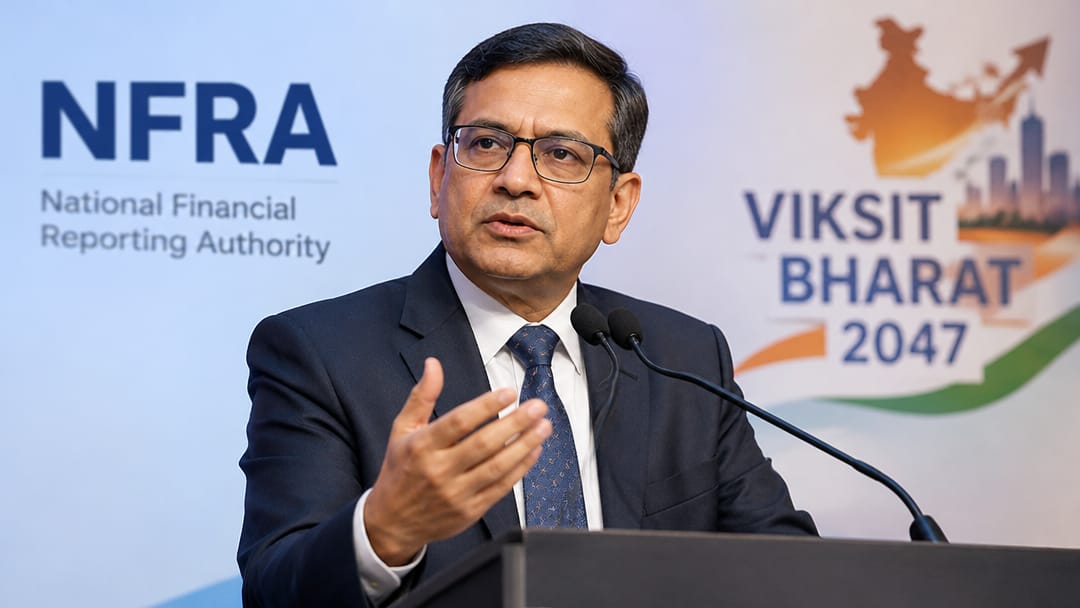
NFRA chief links credible audit oversight directly to India's Viksit Bharat goals
What happened
NFRA Chairperson Nitin Gupta stated that credible financial reporting and independent audit oversight are foundational to India achieving Viksit Bharat status by 2047. Speaking at a Business Standard event, Gupta emphasised that investor confidence, capital formation, and economic growth all depend on reliable audited accounts. NFRA, established under the Companies Act 2013, oversees audit quality for listed and large public interest entities, functioning as India's independent audit regulator separate from the ICAI.
Why it matters
The National Financial Reporting Authority (NFRA) is India's independent audit and accounting regulator, constituted under Section 132 of the Companies Act, 2013. It was operationalised in 2018 following the government notification, partly triggered by high-profile audit failures like the IL&FS crisis. NFRA's mandate covers setting auditing and accounting standards, investigating audit quality lapses, and imposing penalties on auditors of public interest entities — listed companies, large unlisted public companies, and entities above prescribed size thresholds.
Before NFRA, the Institute of Chartered Accountants of India (ICAI) self-regulated the audit profession. The creation of NFRA represented a structural shift: an independent statutory body now disciplines auditors of systemically important entities, removing the self-regulation conflict.
For corporate governance, the connection Gupta draws is direct: financial statements audited by independent, accountable auditors are the primary information source for investors, creditors, and regulators. Weak audit quality distorts price discovery, enables fraud, and undermines market integrity — all concerns central to SEBI's mandate over listed companies.
For SEBI Grade A aspirants, the governance architecture matters: SEBI regulates disclosure and listing obligations; NFRA regulates the auditors who certify those disclosures. The two regulators sit at different points of the same accountability chain. Exam questions often test whether aspirants understand which regulator does what, and the statutory basis for each body's authority.
Before NFRA, the Institute of Chartered Accountants of India (ICAI) self-regulated the audit profession. The creation of NFRA represented a structural shift: an independent statutory body now disciplines auditors of systemically important entities, removing the self-regulation conflict.
For corporate governance, the connection Gupta draws is direct: financial statements audited by independent, accountable auditors are the primary information source for investors, creditors, and regulators. Weak audit quality distorts price discovery, enables fraud, and undermines market integrity — all concerns central to SEBI's mandate over listed companies.
For SEBI Grade A aspirants, the governance architecture matters: SEBI regulates disclosure and listing obligations; NFRA regulates the auditors who certify those disclosures. The two regulators sit at different points of the same accountability chain. Exam questions often test whether aspirants understand which regulator does what, and the statutory basis for each body's authority.
🔒
Key figure and date from this topic
Specific number or threshold to remember
Policy or regulatory implication