Article 19 freedoms are for citizens only — restrictions decide most cases
What happened
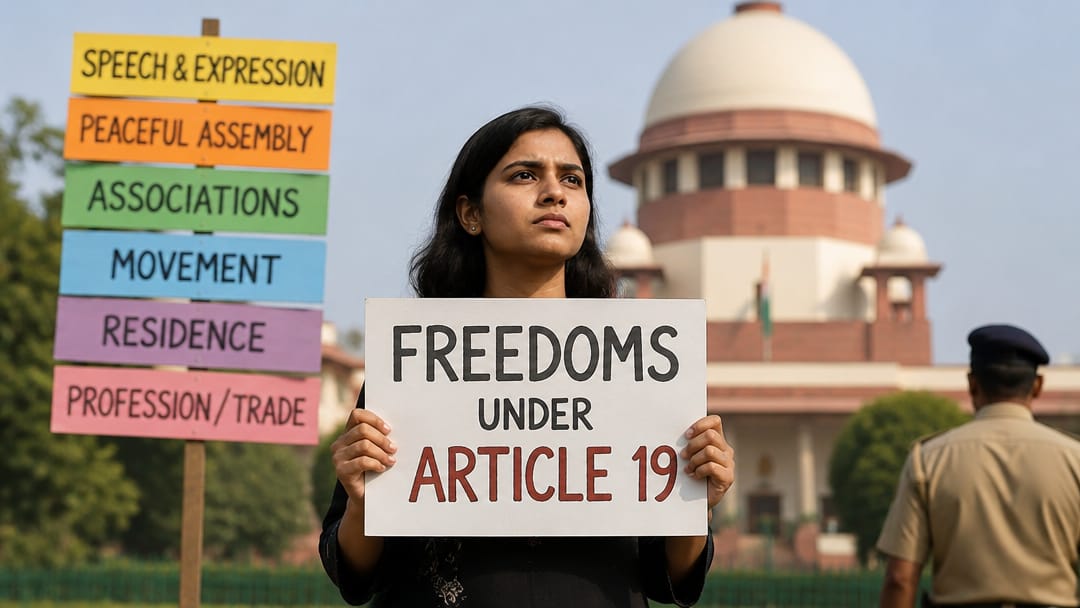
Article 19 of the Indian Constitution grants six fundamental freedoms to citizens: speech and expression, peaceful assembly, forming associations, free movement, residence, and profession or trade. Each freedom is immediately paired with a State power to impose reasonable restrictions under Articles 19(2) to 19(6). The right to property, once Article 19(1)(f), was removed by the 44th Amendment in 1978 and relocated to Article 300A as a statutory right. Article 19 is unavailable to foreign nationals and corporate entities.
Why it matters
Article 19 operates on a paired architecture: every freedom in Article 19(1) has a corresponding restriction clause in Articles 19(2) through 19(6). This design means virtually all litigation under Article 19 is not about whether the freedom exists but whether the State's restriction was reasonable and fell within constitutionally permitted grounds.
The doctrine of reasonable restriction has three essential elements that courts examine: (1) the restriction must be authorised by law — an executive order alone is insufficient; (2) the restriction must fall strictly within the grounds specified for that particular sub-clause — grounds permissible for speech cannot justify a restriction on movement; and (3) the restriction must satisfy the proportionality test — it must not be excessive relative to the legitimate aim pursued.
A critical citizenship boundary separates Article 19 from Article 21. Article 21 protects 'any person' — it is universal. Article 19 protects only 'citizens.' This means foreign nationals in India have no Article 19 claim. Corporations are not citizens, but their individual shareholders retain personal Article 19 rights.
The 44th Constitutional Amendment (1978) removed the right to property from Part III entirely, shifting it from Article 19(1)(f) to Article 300A. This downgrade from fundamental right to legal right is a recurring examination point because it changed both the standard of judicial review and the available remedies.
In the exam context, the examiner typically presents a passage from a Supreme Court ruling and tests whether the aspirant can identify: the specific freedom engaged, the specific restriction clause applicable, and whether the court's proportionality reasoning validates or invalidates the State action on novel facts.
OECD sets a 15% global minimum tax floor for large multinationals
What happened
On 20 December 2021, the OECD/G20 Inclusive Framework released Model Global Anti-Base Erosion (GloBE) Rules under Pillar Two of BEPS 2.0. These rules establish a 15% global minimum corporate tax rate for multinational enterprises with annual revenues exceeding €750 million. Pillar One reallocates taxing rights to market jurisdictions. Together, the two pillars aim to curb profit-shifting to low-tax havens and ensure large corporations pay a minimum level of tax wherever they operate.
Why it matters
BEPS 2.0 is the OECD/G20 response to base erosion and profit shifting — the practice by which multinationals legally move profits to low-tax jurisdictions, reducing tax revenue for countries where actual economic activity occurs.
Pillar One addresses where tax is paid. It reallocates a portion of profits (Amount A) of the largest and most profitable multinationals (revenue >€20 billion, profitability >10%) to market jurisdictions — countries where consumers are located — regardless of physical presence. This is especially significant for digital economy companies like Google and Meta that generate revenue from a country without having a taxable presence there.
Pillar Two addresses how much tax is paid. The GloBE rules introduce an effective minimum tax rate of 15% via two interlocking domestic rules: the Income Inclusion Rule (IIR), where a parent company pays a top-up tax if a subsidiary is taxed below 15%, and the Undertaxed Profits Rule (UTPR), a backstop mechanism. A third rule — the Subject to Tax Rule (STTR) — applies to certain payments between related parties.
For India, BEPS 2.0 is significant on multiple fronts. India is a member of the Inclusive Framework, stands to gain from Pillar One's reallocation of digital profits, and has already enacted a Qualified Domestic Minimum Top-Up Tax (QDMTT) to retain revenue domestically. India's Equalisation Levy (digital tax) is expected to be withdrawn as part of the Pillar One deal. These dynamics sit at the intersection of international taxation, fiscal sovereignty, and G20 economic diplomacy — all high-frequency UPSC themes.
Chhattisgarh HC rules fatwa cannot override an individual's legal rights
What happened
The Chhattisgarh High Court has ruled that a fatwa — a religious opinion issued by an Islamic authority — carries no binding legal force and cannot be enforced in a manner that prejudices an individual's legal rights. The court's ruling reaffirms that religious edicts issued by unofficial bodies have no standing in Indian civil or criminal law, and that constitutional rights of individuals cannot be overridden by such pronouncements under any circumstances.
Why it matters
A fatwa is a non-binding religious opinion issued by a qualified Islamic scholar (mufti) on a question of Islamic law. In India, fatwas are frequently issued by bodies such as Darul Uloom Deoband or local Sharia courts (Dar-ul-Qazas), but they have no statutory backing and cannot be enforced by state machinery.
The Chhattisgarh HC's ruling is consistent with the Supreme Court's landmark position in Vishwa Lochan Madan v. Union of India (2014), where the Supreme Court unanimously held that fatwas have no legal sanction, cannot be enforced by any authority, and any attempt to do so would be unconstitutional. The Court held that Dar-ul-Qazas and Sharia courts are neither courts nor tribunals under Indian law — they derive no authority from any statute.
Constitutionally, this ruling engages several fundamental rights: Article 14 (equality before law), Article 19(1)(a) (freedom of speech and expression), Article 21 (right to life and personal liberty), and Article 25 (freedom of conscience and religion). The key principle is that while Article 25 protects the right to practise religion, it does not permit religious directives to override statutory rights or constitutional guarantees of other individuals.
The distinction the courts consistently draw is between a fatwa as personal religious guidance — which is protected speech — and a fatwa as an enforceable directive that curtails another person's freedom, which is constitutionally impermissible. This is the classic rights-versus-rights balancing the examiner tests under constitutional law passages.
India's growth-vs-nature tension put under the spotlight at Eco Warrior Awards 2026
What happened
The Eco Warrior Awards 2026 raised a central question in India's development debate: can the country sustain rapid economic growth while preserving its forests, rivers, wildlife, and ecosystems? The event recognised individuals and organisations working at the intersection of environment and development. It highlighted the structural tension between infrastructure expansion and ecological protection — a conflict that sits at the core of India's environmental policy, NDC commitments, and biodiversity obligations under international conventions.
Why it matters
India faces a classic development-environment paradox: its growth imperatives demand land, water, energy, and infrastructure, yet its forest cover, river systems, and biodiversity hotspots are legally and ecologically constrained. This tension is not merely rhetorical — it is embedded in real policy instruments.
India's Nationally Determined Contribution (NDC) under the Paris Agreement commits to creating an additional carbon sink of 2.5 to 3 billion tonnes of CO₂ equivalent through forest and tree cover by 2030. Simultaneously, the Forest Conservation Act (now the Van Sanrakshan Evam Samvardhan Adhiniyam, 2023) governs diversion of forest land for non-forest use, with the compensatory afforestation mechanism as a mitigation tool.
Biodiversity protection falls under the Biological Diversity Act, 2002, which operationalises India's obligations under the Convention on Biological Diversity (CBD) and its Nagoya Protocol. The Kunming-Montreal Global Biodiversity Framework (2022) further commits nations to protect 30% of land and oceans by 2030 — the '30x30' target — which India endorsed.
River conservation intersects with the National Mission for Clean Ganga (Namami Gange) and the broader National Water Policy. Environmental Impact Assessments (EIA), governed by the Environment Protection Act, 1986, are the procedural checkpoint for balancing growth projects against ecological costs.
Awards like Eco Warrior serve as civil-society signals of which conservation approaches are working on the ground — the kind of grassroots implementation that UPSC tests through biodiversity management committees, biosphere reserves, and community-led conservation models.
IDBI Bank privatisation approved: set to become India's largest FDI in finance
What happened
The government has approved the strategic restructuring of IDBI Bank Ltd., which involves disinvestment of government and LIC stakes to a strategic investor. Once completed, the transaction is expected to become the largest foreign direct investment ever received in India's financial sector. The move is part of India's broader disinvestment programme aimed at reducing the state's footprint in public sector banks and unlocking value from government-owned financial institutions.
Why it matters
IDBI Bank has a unique ownership structure: the Government of India and LIC together hold a majority stake, making it effectively a government-controlled bank. The strategic restructuring involves selling a combined stake to a private strategic investor, which could include a foreign entity, thereby triggering FDI into the banking sector.
This disinvestment is significant for several reasons. First, it represents a policy shift — moving away from the traditional model of state-owned banking toward private participation in a systemically important bank. Second, since the buyer could be a foreign entity, the transaction would constitute FDI, and given the size of IDBI Bank's balance sheet, it would be the largest single FDI inflow India's financial sector has ever seen.
For RBI, this raises regulatory questions: who can hold a banking licence, fit-and-proper criteria for large shareholders, and whether the new owner requires an RBI-approved ownership structure. RBI's guidelines on ownership and governance in private sector banks become directly relevant.
For UPSC aspirants, this connects to broader themes: disinvestment policy, the role of LIC as a government instrument, financial sector reforms since 1991, and governance of public sector enterprises. IDBI Bank was originally established under the IDBI Act, 1964, as a development finance institution before converting to a universal bank. Its transformation from DFI to commercial bank to privatisation candidate itself tells the story of India's evolving financial architecture.
AI, drones, and GPS deployed for Indian wildlife protection at EWA 2026
What happened
At the Eco Warrior Awards 2026 Conclave, experts outlined how artificial intelligence, drone surveillance, IoT sensors, and GPS tracking are being integrated into India's forest and wildlife protection systems. The technologies enable real-time poaching alerts, animal movement monitoring, and habitat mapping. The conclave highlighted that these tools complement — but do not replace — on-ground forest staff, and that data connectivity in remote forest areas remains a significant operational barrier to wider deployment.
Why it matters
India's wildlife conservation framework rests on two statutory pillars: the Wildlife Protection Act, 1972 and the Forest Conservation Act, 1980. Protected areas — National Parks, Wildlife Sanctuaries, Tiger Reserves, and Biosphere Reserves — are managed under these laws by state forest departments with central coordination through the National Tiger Conservation Authority (NTCA) and Wildlife Crime Control Bureau (WCCB).
Technology is now layered on top of this framework. Key tools include:
• Drones (UAVs): Used for aerial patrolling, anti-poaching surveillance, and post-fire damage assessment. NTCA has piloted drone deployment in several tiger reserves. • AI-based camera traps: Machine learning algorithms identify individual animals by stripe or spot patterns (e.g., tigers, leopards), enabling population census without physical capture. • GPS/satellite collaring: Tracks migration corridors and human-wildlife conflict hotspots. Critical for elephant corridors and Project Tiger reserves. • IoT acoustic sensors: Detect chainsaw sounds or gunshots and trigger real-time alerts to forest rangers. • Bioacoustic monitoring: AI analyses recorded soundscapes to assess biodiversity health.
India's M-STrIPES (Monitoring System for Tigers — Intensive Protection and Ecological Status) is the official digital platform for tiger reserve management, using GIS and mobile data collection. The integration of AI into such platforms represents the current frontier. The examiner will test both the technology names and the institutional frameworks that govern their deployment.