Finance Ministry nowcast puts Q2 FY27 GDP growth at 7.35%
What happened
India's Ministry of Finance, using its nowcasting model, estimates GDP growth at 7.35 per cent for the second quarter of FY27 (July–September 2026), according to its monthly economic report. The projection signals continued resilience but is accompanied by acknowledged downside risks. Nowcasting differs from official GDP estimates by using high-frequency real-time indicators to generate forward-looking growth readings before formal data is released by the National Statistical Office.
Why it matters
A nowcasting model uses high-frequency, real-time data — such as GST collections, PMI readings, power consumption, rail freight, and credit offtake — to estimate GDP growth before the National Statistical Office publishes official quarterly figures. This is important because official GDP data arrives with a lag of roughly two months after the quarter ends, creating a window during which policymakers and analysts rely on such proxies.
The Finance Ministry's Monthly Economic Review is the vehicle for this estimate. When it projects 7.35% for Q2 FY27, it is drawing on contemporaneous indicators rather than a structural model alone.
For exam purposes, understand three distinctions: (1) Nowcasting vs. forecasting — nowcasting uses current-period data to estimate the present, while forecasting projects future periods; (2) NSO vs. Ministry of Finance — the NSO publishes the Advance Estimate, First Revised Estimate, and Second Revised Estimate, while the Finance Ministry's nowcast is an independent real-time tool; (3) India's GDP measurement uses the expenditure method (C+I+G+NX) and the production/value-added method, with the base year currently 2011-12.
The 7.35% figure, if realised, would place India comfortably among the fastest-growing major economies, consistent with IMF and RBI projections for FY27. The caveat of 'risks' typically refers to global trade uncertainty, geopolitical shocks, and domestic inflation pressures — all of which affect the MPC's rate decisions and fiscal consolidation calculus.
PM-KISAN reaches 9.34 crore farmers with ₹6,000 annual direct cash transfer
What happened
PM-KISAN, the Pradhan Mantri Kisan Samman Nidhi scheme, provides direct income support of ₹6,000 per year to eligible farmer families across India, disbursed in three equal instalments of ₹2,000 each. Currently benefiting over 9.34 crore farmers, it operates through Direct Benefit Transfer. ICAR-CIFRI observed PM-KISAN Utsav Diwas alongside Khet Jagrukta Diwas, highlighting the scheme's role in strengthening rural economies and promoting awareness among farming communities about government welfare outreach.
Why it matters
PM-KISAN (Pradhan Mantri Kisan Samman Nidhi) was launched in February 2019 under the Ministry of Agriculture and Farmers' Welfare. It is a Central Sector Scheme — meaning it is fully funded by the Government of India, unlike Centrally Sponsored Schemes where states share costs. This distinction is frequently tested.
The scheme provides ₹6,000 per year in three instalments of ₹2,000 each, credited directly to the bank accounts of eligible farmer families through the Direct Benefit Transfer (DBT) mechanism. This eliminates middlemen and reduces leakage, making it a model for last-mile financial delivery.
Eligibility covers all landholding farmer families with cultivable land, subject to exclusion criteria: income taxpayers, institutional landholders, constitutional post-holders, and serving/retired government employees above a threshold are excluded. The scheme uses the Aadhaar-seeded land records database for identification.
For NABARD aspirants, the scheme connects to rural credit: the cash transfer supplements farm income, reducing distress borrowing and improving loan repayment capacity. For UPSC aspirants, PM-KISAN exemplifies DBT-based welfare architecture under the JAM Trinity (Jan Dhan–Aadhaar–Mobile). The current beneficiary count of 9.34 crore is a precision figure the examiner will test. PM-KISAN Utsav Diwas is observed on February 24, marking the scheme's anniversary.
GST show-cause notices must now be split year-by-year, fraud claims need proof
What happened
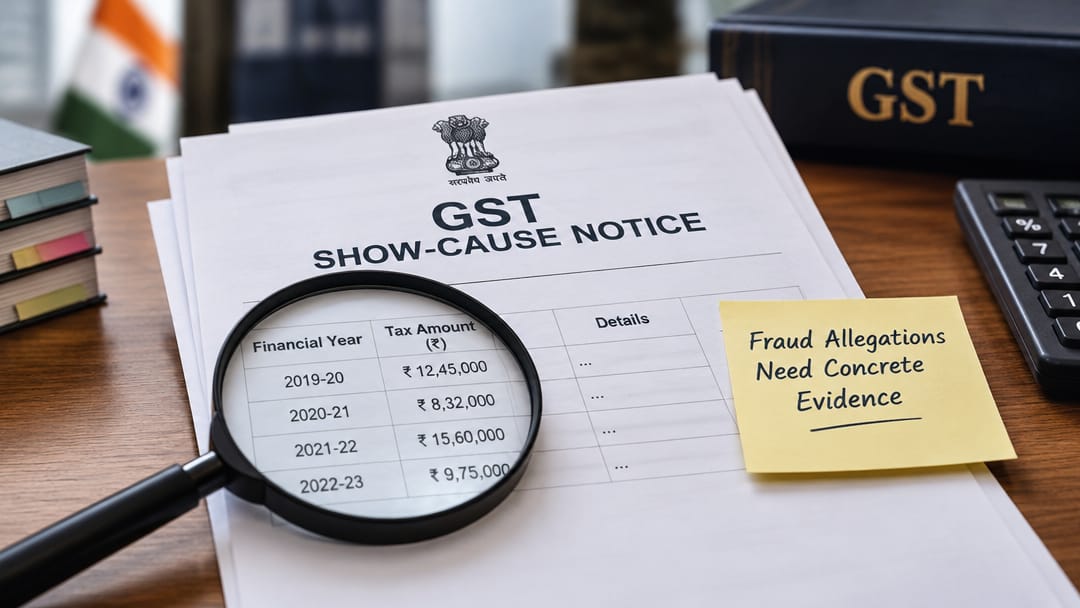
Tax authorities have been instructed that a single show-cause notice cannot bundle multiple years of GST demands without specifying the tax amount owed for each year individually. Officers must also substantiate fraud allegations with concrete evidence rather than making blanket claims. This procedural reform is aimed at improving taxpayer rights and enforcement quality under the GST framework, ensuring that notices are precise, year-specific, and legally defensible before adjudication proceeds.
Why it matters
A show-cause notice (SCN) under the GST Act is the first formal step in tax demand proceedings. Previously, officers sometimes clubbed multiple financial years into a single notice, making it difficult for taxpayers to understand or contest the specific demand for each period. The new instruction mandates year-wise disaggregation of tax demands within every SCN.
This reform has two key dimensions. First, procedural clarity: each year's demand must carry its own tax quantum, so the taxpayer knows exactly what is being alleged for each period. Second, evidentiary burden: if an officer alleges fraud, suppression, or wilful misstatement — provisions that extend the limitation period for issuing notices from 3 years to 5 years under Section 74 of the CGST Act — the allegation must be backed by substantive evidence, not assumed.
For NABARD aspirants, this matters because GST compliance affects agri-input suppliers, rural cooperative businesses, and entities that NABARD refinances. Unjustified multi-year bundled notices can disrupt cash flows, inflate working capital needs, and indirectly raise the cost of rural credit. GST enforcement quality is therefore a fiscal governance issue with downstream effects on agricultural credit ecosystems and cooperative bank operations.