ISRO targets four launch pads by 2029, adds SSLV spaceport in Tamil Nadu
What happened
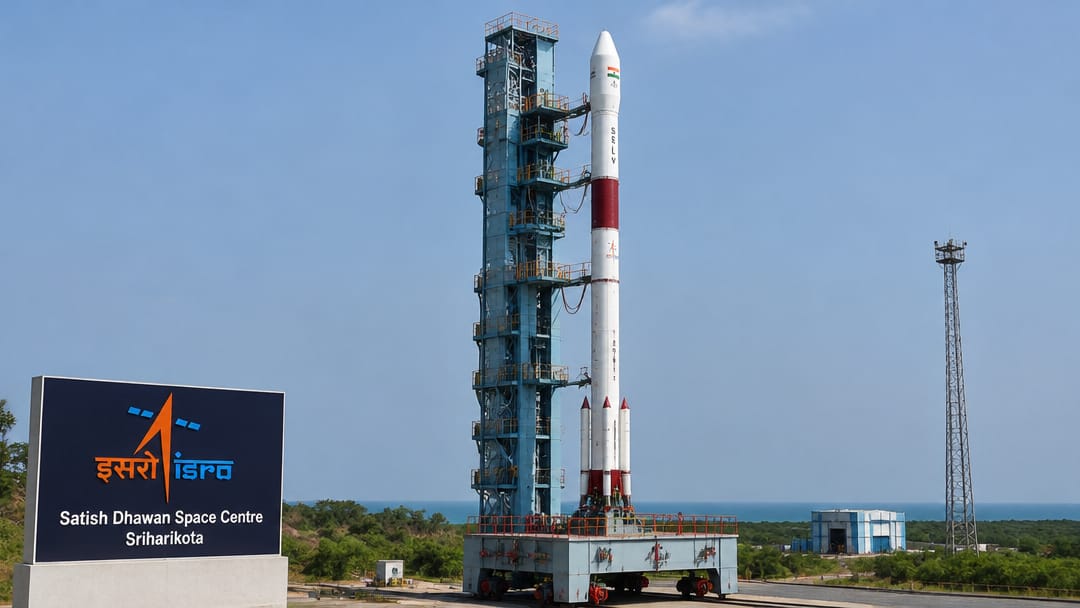
ISRO Chairman V Narayanan announced plans for four operational launch pads by 2029, including a dedicated 2,000-acre Small Satellite Launch Vehicle complex at Kulasekarapattinam in Tamil Nadu's Tuticorin district. The agency is preparing its first uncrewed Gaganyaan test within two months, with two more uncrewed flights before a crewed mission. ISRO also plans Chandrayaan-5, a collaborative lunar mission with Japan featuring a 350-kg rover for 100-day surface experiments. Private sector partnerships will support commercial operations, though ISRO itself will not be privatised.
Why it matters
This announcement bundles three exam-relevant threads: launch infrastructure expansion, human spaceflight progress, and international lunar collaboration.
On infrastructure: India currently operates launch pads at Satish Dhawan Space Centre, Sriharikota (Andhra Pradesh). The new Kulasekarapattinam spaceport in Tuticorin district is significant because its southern coastal location gives SSLV missions a direct southward trajectory over the sea, reducing range safety constraints and improving orbital insertion efficiency for small satellites.
On Gaganyaan: India's first human spaceflight programme involves four astronaut-designates (Gaganyaatris) who trained in Russia. The mission architecture includes uncrewed test flights first — the crew module must pass environmental control, life support, and crew escape system validations. The ~8,000 ground experiments already completed show the programme's maturity. ISRO has already conducted the Crew Escape System (CES) pad abort test in 2023.
On Chandrayaan-5: Unlike Chandrayaan-3 (India-only soft lander/rover), Chandrayaan-5 is a joint mission with JAXA (Japan Aerospace Exploration Agency). The 350-kg rover is substantially heavier than Pragyan (26 kg), indicating a more ambitious surface science mandate over 100 days.
On privatisation: The In-Space (Indian National Space Promotion and Authorisation Centre) framework, established in 2020, enables private players like Skyroot Aerospace to operate within India's space sector without privatising ISRO itself — a distinction examiners test directly.
RBI raises repo rate to 5.5%, shifts stance to calibrated tightening
What happened
The RBI's MPC unanimously raised the repo rate by 25 basis points to 5.5 per cent at its October 5–7 meeting — the first hike in nearly four years. The stance shifted from neutral to calibrated tightening, ruling out near-term cuts. Governor Sanjay Malhotra flagged broadening inflation: 37 per cent of CPI basket commodities recorded inflation above 4 per cent in August, up from 20 per cent in March. Future hikes remain data-dependent.
Why it matters
This MPC decision tests several layered concepts that examiners repeatedly probe.
**The LAF Corridor and Repo Rate:** The repo rate is the rate at which RBI lends overnight funds to commercial banks under the Liquidity Adjustment Facility. A hike raises borrowing costs for banks, which transmit higher rates to consumers and firms, cooling credit demand and thereby inflation. The transmission mechanism runs: repo rate → bank lending rates → credit growth → aggregate demand → inflation.
**Stance Shift — Neutral to Calibrated Tightening:** Under the inflation targeting framework (IT framework, 2016), the MPC manages policy through both the rate and the stance. 'Neutral' means the next move could go either way. 'Calibrated tightening' explicitly rules out cuts — only a hike or a pause is possible. This is a stronger signal than a rate move alone because it shapes market expectations.
**Inflation Targeting Framework:** India adopted flexible inflation targeting in 2016. The target is 4% CPI with a tolerance band of ±2% (lower: 2%, upper: 6%). If inflation breaches the upper tolerance for three consecutive quarters, the RBI must submit a report to the government explaining the breach and remedial steps. The current data point — 37% of CPI commodities above 4% — signals broadening, not just headline, inflation.
**MPC Composition:** The six-member MPC has three RBI members (Governor as chair, Deputy Governor, one RBI officer) and three external members appointed by the Government of India. Decisions require a majority; the Governor has a casting vote in a tie. A unanimous vote, as here, is exam-notable.
**Second-Round Effects:** Supply shocks (e.g., food or fuel price spikes) can feed into wages and broader prices — these 'second-round effects' are what central banks fear most because they entrench inflation expectations.
UCC enacted in Uttarakhand, 21 NDA states targeted by 2029
What happened
Uttarakhand became the first state to enact a Uniform Civil Code in 2024, replacing personal laws governing marriage, divorce, inheritance, and adoption for all residents except Scheduled Tribes. The BJP-led NDA government has set a target of implementing UCC across 21 states by 2029. The UCC is directed by Article 44 of the Constitution as a Directive Principle of State Policy, making it aspirational but not judicially enforceable as a fundamental right.
Why it matters
The Uniform Civil Code refers to a single set of civil laws governing personal matters — marriage, divorce, maintenance, inheritance, and adoption — applicable to all citizens regardless of religion. Currently, India operates under religion-specific personal laws: the Hindu Marriage Act, Muslim Personal Law, Indian Christian Marriage Act, and Parsi Marriage and Divorce Act, among others.
Article 44 of the Constitution places UCC in Part IV as a Directive Principle of State Policy (DPSP). DPSPs are non-justiciable — a citizen cannot go to court demanding UCC enforcement — but courts have repeatedly nudged Parliament toward it. The Supreme Court first called for UCC in Shah Bano (1985) and again in Sarla Mudgal (1995), observing that personal law conflicts produce unjust outcomes, especially for women.
The constitutional tension is critical for CLAT PG: UCC intersects with Article 25 (freedom of religion), Article 26 (right to manage religious affairs), and Article 14 (equality). Minority communities argue personal law is part of religious identity protected under Articles 25–26. Proponents argue inequality within personal laws — especially in Muslim divorce, Hindu inheritance, and Christian adoption — violates Article 14.
Uttarakhand's 2024 UCC Act is significant because it is the first sub-national implementation. It exempts Scheduled Tribes — a deliberate carve-out that itself raises Article 14 questions about differential treatment. For CLAT PG, the examiner will test whether you understand why a DPSP cannot be directly enforced, how personal law interacts with fundamental rights, and what the courts have said about the state's obligation.
RBI MPC meets June 2026 with repo rate at 5.25% amid crude oil inflation risk
What happened
The RBI's Monetary Policy Committee began its June 2026 three-day meeting under Governor Sanjay Malhotra, with markets widely expecting the repo rate to hold at 5.25%. The key tension is rising crude oil prices, which threaten to push inflation higher and complicate the MPC's accommodative stance. Having already cut rates earlier in 2025-26, the committee faces pressure to pause and assess transmission before any further easing of monetary conditions.
Why it matters
The MPC operates India's flexible inflation targeting framework, mandated to keep CPI inflation at 4% with a ±2% band. The repo rate — the rate at which RBI lends overnight funds to commercial banks — is the primary policy instrument. When MPC cuts repo, borrowing costs fall, credit expands, and demand rises; when it holds or hikes, it signals caution about inflation.
The LAF (Liquidity Adjustment Facility) corridor frames daily liquidity: the repo rate is the ceiling for borrowing from RBI, and the Standing Deposit Facility (SDF) rate is the floor for parking funds with RBI. The policy rate sits at the midpoint, giving the corridor its shape.
Crude oil prices matter because India imports roughly 85% of its oil. A sustained rise feeds directly into transport costs, manufacturing input costs, and food supply chains — creating cost-push inflation that the MPC cannot easily offset with rate cuts without risking a price spiral. This is the classic supply-side bind: cutting rates to support growth risks stoking inflation that is already being pushed up by external commodity prices.
The June 2026 pause scenario reflects a 'wait and watch' posture: prior cuts have been made, and the MPC now waits to see whether credit growth and investment respond before deciding the next move. This transmission lag — typically 2–3 quarters — is central to understanding why the MPC does not adjust rates every meeting.
Rising bond yields after RBI's October policy could raise India's interest bill
What happened
After the RBI's October 2024 monetary policy review, government bond yields have risen sharply, threatening to increase the central government's interest payment burden for the rest of the fiscal year. When yields rise on newly issued or rolled-over debt, the cost of borrowing goes up, squeezing the fiscal deficit target. Higher interest payments crowd out capital expenditure, tightening the government's room to spend on infrastructure and social programmes without breaching the deficit ceiling.
Why it matters
Government bond yields and fiscal arithmetic are tightly linked through a mechanism most aspirants underestimate. When the RBI holds or raises policy rates — or signals a hawkish stance — bond market participants demand higher yields on government securities (G-Secs) to compensate for the expectation that money will remain expensive. The yield on the benchmark 10-year G-Sec is the reference rate for sovereign borrowing cost.
India's central government borrows heavily through dated securities and Treasury Bills throughout the year under a market borrowing programme announced in the Union Budget. When yields rise mid-year — after that programme is already underway — the government must either pay higher coupon rates on fresh issuances or accept higher cut-off yields at weekly auctions. Both outcomes increase the interest outgo beyond what was budgeted.
Interest payments are the single largest item in India's revenue expenditure, consuming over 40 paise of every rupee the government earns in revenue receipts. A sustained yield spike therefore compresses the fiscal space available for discretionary spending. The government faces a trilemma: cut capital expenditure (crowding-out), accept a wider fiscal deficit (breaching the FRBM glide path), or reduce market borrowing (tightening liquidity further).
This connects to the LAF corridor: if the RBI wants to bring yields down it can conduct Open Market Operations (OMO) — purchasing G-Secs from the secondary market — injecting liquidity and pushing prices up (yields down). The absence of such OMOs signals the RBI's tolerance for tighter financial conditions, which is itself a transmission tool for inflation control.
India–EU Free Trade Agreement targeted for December 2026 during Modi's Brussels visit
What happened
India and the European Union are targeting December 2026 to sign a Free Trade Agreement, potentially during Prime Minister Modi's visit to Brussels. Negotiations, which originally began in 2007 and stalled in 2013, were relaunched in 2022. The deal would cover goods, services, investment, and geographical indications. The EU is India's largest trading partner bloc, with bilateral trade exceeding €120 billion annually, making this one of India's most consequential trade negotiations.
Why it matters
The India–EU FTA, also called the Broad-based Trade and Investment Agreement (BTIA), has been among the most protracted trade negotiations in modern history. Talks began in 2007 under the EU–India Strategic Partnership framework but collapsed in 2013 over disagreements on tariff reductions for automobiles and wines, data security recognition, and market access for generic pharmaceuticals and professional services.
Negotiations were formally relaunched in June 2022 at the India–EU Leaders' Meeting in New Delhi. The revived talks run on three parallel tracks: a Free Trade Agreement (goods and services), an Investment Protection Agreement, and a Geographical Indications Agreement.
For India, the strategic calculus has shifted. The EU represents roughly 15% of India's total exports. Post-Brexit, the UK trade deal has been separately negotiated, removing a major variable. The EU's Carbon Border Adjustment Mechanism (CBAM), which taxes carbon-intensive imports from 2026, gives Indian exporters in steel, aluminium, and chemicals a strong incentive to conclude an FTA that includes climate-compatible provisions.
For the EU, India is a hedge against China-dependency in supply chains, especially after the post-pandemic realignment. The EU has also pushed for labour standards, intellectual property enforcement, and public procurement access — all contentious for India.
A December 2026 signing during a Modi–Brussels summit would be politically symbolic and economically transformative, potentially the largest FTA either party has signed by trade value.
Jaishankar sets border peace as precondition for normalising India-China ties
What happened
External Affairs Minister S. Jaishankar stated that restoring peace along the Line of Actual Control is a prerequisite before India-China relations can return to normal. He outlined a phased diplomatic approach: first resolving border friction, then rebuilding trust, and finally expanding broader bilateral engagement. His remarks come after the October 2024 disengagement agreement at Depsang and Demchok ended the standoff that began with the Galwan clash of June 2020.
Why it matters
Jaishankar's framing reflects a deliberate sequencing in India's foreign policy posture toward China — a country with which India shares a 3,488-km border, much of it disputed and governed by no formally demarcated Line of Actual Control (LAC).
The Galwan Valley clash of June 2020 (in eastern Ladakh) marked the deadliest India-China border confrontation since 1967, killing 20 Indian soldiers. It triggered a cascade of diplomatic and economic responses: India banned over 200 Chinese apps, tightened FDI rules requiring government approval for investment from land-bordering countries, and suspended direct flights. These measures remain partly in place.
The October 2024 disengagement deal at Depsang Plains and Demchok — the last two friction points in eastern Ladakh — is significant because it re-established patrolling rights India had lost since 2020. However, Jaishankar's caution that 'border peace is precondition, not outcome' signals India will not rush to restore pre-2020 trade, visa, and diplomatic normalcy simply because troops have stepped back.
The static framework behind this is India's 'Three Mutuals' — mutual respect, mutual sensitivity, and mutual interests — articulated by Jaishankar as the foundational test for the relationship. For UPSC, the key institutional mechanisms include the Working Mechanism for Consultation and Coordination (WMCC), the Special Representatives dialogue (currently paused), and the 1993, 1996, 2005, and 2013 border peace agreements that form the legal backbone of LAC management.
MPC minutes flag rising inflation; economists now expect a repo rate hike in December
What happened
The RBI's Monetary Policy Committee meeting minutes, released after the June 2025 meeting, highlighted rising inflation concerns, with Governor Sanjay Malhotra signalling that rate decisions remain data-dependent. Economists now anticipate a back-to-back repo rate hike in December 2025, reversing the earlier accommodative tilt. The minutes underscore the MPC's vigilance on inflation persistence even as growth concerns linger, marking a potential pivot in India's monetary policy stance.
Why it matters
The MPC operates under India's flexible inflation targeting framework, mandated to keep CPI inflation at 4% (with a ±2% band) under the RBI Act, 1934 (as amended in 2016). The repo rate — the rate at which RBI lends overnight funds to commercial banks against collateral — is the primary policy instrument. When inflation rises persistently above the 4% target, the MPC typically raises the repo rate to make borrowing costlier, which dampens demand and credit growth, eventually cooling prices.
The transmission mechanism works thus: a repo rate hike raises banks' cost of funds → lending rates (MCLR and external benchmark-linked rates) rise → EMIs increase → consumer spending and investment fall → aggregate demand contracts → inflation moderates. However, transmission is not instantaneous; it typically takes 3–4 quarters to fully transmit.
The Liquidity Adjustment Facility (LAF) corridor defines the policy rate band: the Standing Deposit Facility (SDF) rate forms the floor, the repo rate is the policy rate (middle), and the Marginal Standing Facility (MSF) rate is the ceiling. A rate hike shifts this entire corridor upward.
For NABARD aspirants: higher repo rates increase RBI's refinancing cost to NABARD, which can push up agricultural credit costs, affecting rural borrowers directly. This connection between MPC decisions and ground-level credit access is central to NABARD's mandate.
MoEFCC and NBA launch 5-year biodiversity governance project in Tamil Nadu and Meghalaya
What happened
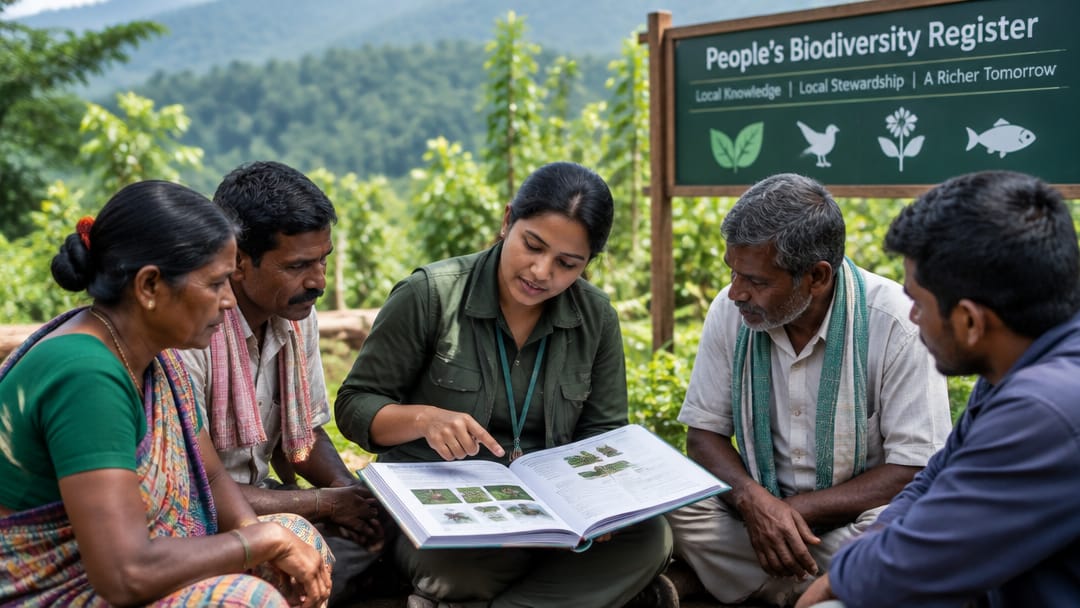
The Ministry of Environment, Forest and Climate Change and the National Biodiversity Authority have jointly launched a five-year project to strengthen grassroots biodiversity governance in Tamil Nadu and Meghalaya. The initiative focuses on empowering Biodiversity Management Committees at the local level, improving People's Biodiversity Registers, and enhancing access and benefit-sharing mechanisms under the Biological Diversity Act, 2002. The two states were chosen to pilot the model before potential national scaling.
Why it matters
This project sits at the intersection of two exam-critical frameworks: the Biological Diversity Act, 2002 (India's domestic implementation of the Convention on Biological Diversity) and the Nagoya Protocol on Access and Benefit-Sharing.
The National Biodiversity Authority (NBA), headquartered in Chennai, is a statutory body established under the Biological Diversity Act, 2002. It operates under MoEFCC and oversees a three-tier structure: NBA at the national level, State Biodiversity Boards (SBBs) at the state level, and Biodiversity Management Committees (BMCs) at the local body level.
BMCs are mandated to prepare People's Biodiversity Registers (PBRs) — comprehensive local records of biological resources, their habitats, traditional knowledge, and current uses. PBRs are the grassroots documentation tool that supports ABS (Access and Benefit-Sharing) claims under the Nagoya Protocol.
The choice of Tamil Nadu and Meghalaya is significant: Tamil Nadu falls within the Western Ghats biodiversity hotspot (one of India's four hotspots), while Meghalaya is part of the Indo-Burma hotspot. Both states have rich traditional knowledge systems tied to forest biodiversity.
The project's five-year horizon aligns with the Kunming-Montreal Global Biodiversity Framework (adopted at COP15, 2022), which set the landmark '30x30' target — protecting 30% of land and oceans by 2030. Strengthening BMCs and PBRs is India's ground-level response to these global commitments.
National Urban Conclave 2026 urges ULBs to cut grant dependence, speed up AMRUT delivery
What happened
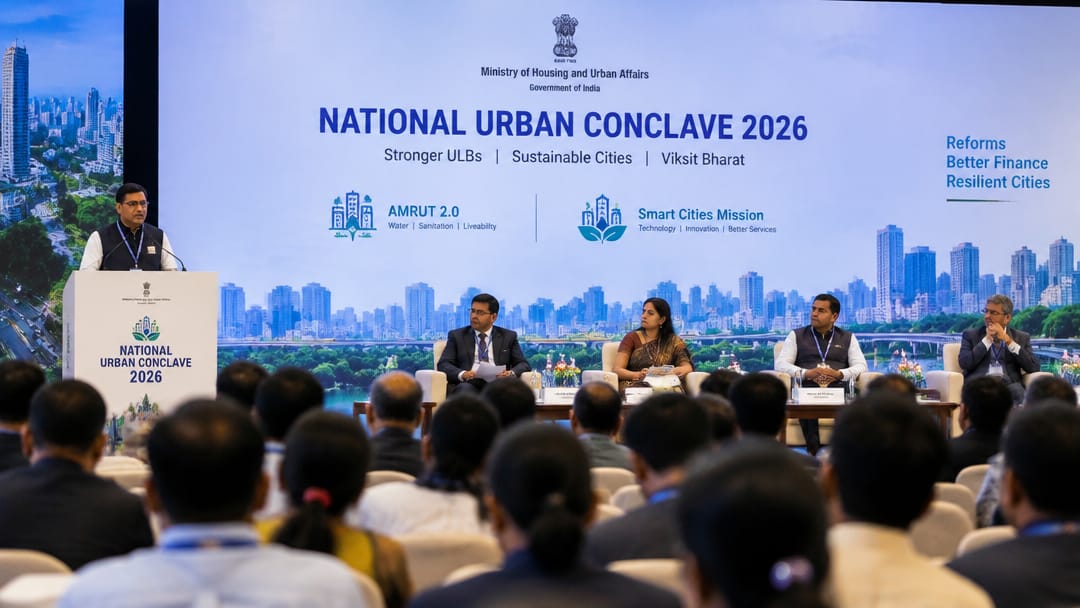
The National Urban Conclave 2026, organised by the Ministry of Housing and Urban Affairs, concluded with a focus on urban governance reforms, financial sustainability of Urban Local Bodies, and progress under flagship schemes like AMRUT 2.0 and the Smart Cities Mission. States and UTs were urged to accelerate implementation, improve property tax collection, and leverage technology for service delivery. The conclave produced actionable recommendations covering municipal finance, water security, and climate-resilient urban planning.
Why it matters
Urban governance in India is primarily a State subject under the 12th Schedule of the Constitution, with 74th Constitutional Amendment (1992) devolving 18 functions to Urban Local Bodies (ULBs). However, ULBs remain financially weak — most depend heavily on Central and State grants rather than own-source revenues like property tax. The National Urban Conclave is an annual platform where the Ministry of Housing and Urban Affairs (MoHUA) aligns States and UTs on implementation of centrally sponsored urban schemes.
AMRUT 2.0 (Atal Mission for Rejuvenation and Urban Transformation) runs from 2021–26 with an outlay of ₹2.77 lakh crore, focusing on water supply, sewerage, urban transport, and greenery in 500 cities. The Smart Cities Mission covers 100 cities with integrated command and control centres, area-based development, and pan-city solutions. PM SVANidhi supports street vendors with micro-credit. PMAY-Urban addresses affordable housing.
The conclave's emphasis on municipal finance reform is policy-critical: stronger ULB revenues reduce dependence on Central transfers and improve bond market access — a dimension relevant to SEBI and RBI from a municipal bond perspective. For NABARD aspirants, the rural-urban continuum and peri-urban credit gaps matter. For UPSC aspirants, the governance, federalism, and 74th Amendment angles are most testable.